
The global financial technology landscape is undergoing an unprecedented transformation, driven by India’s landmark payment rail: the Unified Payments Interface (UPI). Engineered by the National Payments Corporation of India (NPCI), UPI has expanded beyond national borders to redefine cross-border remittances, tourism payments, and real-time merchant settlement.
- The Rise of UPI: From Domestic Success to International Trailblazer
- Driving Forces Behind UPI Global Expansion
- Several key catalysts account for this rapid international growth:
- Tourism and Indian Diaspora Integration
- Reduced Remittance Costs
- Open Architecture & Interoperability
- Financial Inclusion
- Global Footprint: Nations Embracing India’s Payment Tech
- The Regulatory Framework Governing International Instant Payments
- Infrastructure Security & Financial Stability Architecture
- Strategic Impact on the Global Financial Technology Ecosystem
- 1. De-dollarization of Micro-Retail Trade
- 2. Disruption of Credit Card Interchange Models
- 3. Agentic AI & Programmatic Micro-Payments
- The Macroeconomic Impact of UPI on Sovereign Central Banking & FX Reserves
- Direct Local Currency Settlement Corridors
- Technical Comparison: Account-to-Account (A2A) vs. Traditional Card Networks
- Economic Benefits for Small & Medium Enterprises (SMEs)
- The Broader FinTech Ecosystem: Innovations Shaping Digital Wealth
- 1. Credit Lines on UPI
- 2. Conversational Voice Payments
- 3. Central Bank Digital Currencies (CBDC) Interoperability
- Establishing Balance Through Authentic Worship
- FAQs on UPI Global Expansion & Financial Tech
By eliminating high processing fees and intermediate delays, UPI global expansion is democratizing digital transactions across Asia, Europe, and the Middle East. This blog dives into the rapid rise of real-time financial technology, international payment integration, cross-border transactions, and a deeper reflection on true peace in an increasingly fast-driven material society.
The Rise of UPI: From Domestic Success to International Trailblazer
Digital payments have rapidly transitioned from a luxury to an everyday necessity. Introduced to simplify peer-to-peer (P2P) and person-to-merchant (P2M) transfers, the Unified Payments Interface (UPI) has developed into one of the most efficient real-time retail payment architectures on Earth. Operating on a mobile-first, interoperable system, UPI links multiple bank accounts into a single smartphone application, allowing seamless instant fund transfers using virtual payment addresses, QR codes, or phone numbers.
The exponential scale of domestic adoption set the base for international ambition. In India, UPI handles dozens of billions of transactions each month, accounting for over 80% of all domestic digital payment volume. This incredible transaction volume-driven by zero-to-low MDR (Merchant Discount Rate) structures and widespread QR code deployment-established a blueprint that international banking institutions and sovereign finance ministries could no longer ignore.
Driving Forces Behind UPI Global Expansion
The expansion of UPI international cross-border transactions is guided by NPCI International Payments Limited (NIPL), the dedicated international arm of the NPCI. Through strategic bilateral arrangements, public-private payment linkages, and merchant integration agreements, NIPL has positioned UPI as a viable, low-cost alternative to legacy payment networks like SWIFT, Visa, and Mastercard for everyday retail commerce.
Several key catalysts account for this rapid international growth:
Tourism and Indian Diaspora Integration
Millions of Indian tourists, students, and expatriates travel abroad annually. Enabling UPI at international retail destinations eliminates currency conversion friction, high foreign exchange markup fees, and cash handling challenges.
Reduced Remittance Costs
Cross-border remittances traditionally carry high transaction fees ranging from 3% to 8%. Direct linkage between domestic instant payment rails drastically reduces overhead costs for cross-border money transfers.
Open Architecture & Interoperability
Unlike closed-loop digital wallets, UPI relies on open APIs that easily interface with existing banking software, central bank digital rails, and foreign QR infrastructure.
Financial Inclusion
The low cost of acquiring merchants via software-based QR codes enables small vendor adoption in partner countries without requiring expensive Point-of-Sale (POS) hardware.
Global Footprint: Nations Embracing India’s Payment Tech
The international footprint of UPI spans prominent global commerce and travel hubs:
Singapore: The bilateral linking of India’s UPI with Singapore’s PayNow allows users of participating bank apps in both countries to initiate instant cross-border fund transfers without navigating traditional banking clearing houses.
France: Through partnerships with Lyra Network, Indian visitors can pay via UPI QR codes at iconic destinations like the Eiffel Tower and major retail centers across Paris.
UAE and Gulf Cooperation Council (GCC): Partnerships with payment aggregators such as Mashreq’s Neopay allow Indian expatriates and travelers to make instant payments across retail stores, dining venues, and duty-free centers throughout the UAE and Qatar.
Sri Lanka, Nepal, and Bhutan: Neighboring economies have deeply integrated QR payment networks with UPI, boosting cross-border regional trade, tourism revenue, and informal micro-transactions.
The Regulatory Framework Governing International Instant Payments
The international expansion of the Unified Payments Interface (UPI) relies on strict cross-border regulatory frameworks. When NPCI International Payments Limited (NIPL) partners with foreign central banks or payment gateways, it works directly within bilateral monetary arrangements.
Compliance with FEMA and AML Standards
To facilitate transactions across international borders, UPI operations adhere to guidelines established under India’s Foreign Exchange Management Act (FEMA) alongside international Anti-Money Laundering (AML) and Countering the Financing of Terrorism (CFT) protocols.
- KYC Integration: Every international transaction requires full Know Your Customer (KYC) compliance from the originating domestic account.
- Capital Outflow Regulations: Cross-border merchant payments and peer-to-peer (P2P) transfers made via UPI count against the Reserve Bank of India’s (RBI) Liberalised Remittance Scheme (LRS) caps.
- Real-Time Fraud Monitoring: Dynamic risk scoring models analyze transactions for location mismatches, unusual velocity spikes, and high-risk merchant profiles before authorizing cross-border transfers.
Infrastructure Security & Financial Stability Architecture
Security remains a primary focus in expanding real-time retail payment networks internationally. UPI utilizes an end-to-end multi-tiered security structure designed to maintain systemic stability across connected nations.
Also read :Engineers Day 2026: Know About The Principal Engineer Who Has Engineered This Entire Universe?
Hardware-Level Device Binding:
UPI applications authenticate transactions only through the primary smartphone hardware and registered SIM card, preventing unauthorized remote access or credential cloning.
Two-Factor Authentication (2FA):
Every outgoing payment requires explicit input of a secure 4-digit or 6-digit UPI PIN, ensuring that stolen session tokens or logged-in devices cannot complete transactions without user authorization.
Encrypted Inter-Bank Tunneling:
Transaction payloads are fully tokenized and transmitted over encrypted network channels, preventing intermediate data interception during transit between cross-border clearing houses.
Strategic Impact on the Global Financial Technology Ecosystem
The global trajectory of UPI introduces key developments across fintech, corporate treasury, and sovereign monetary policy:
1. De-dollarization of Micro-Retail Trade
By enabling direct currency pairing (such as INR-AED, INR-SGD, or INR-KHR) for everyday merchant transactions, UPI reduces reliance on USD-denominated clearing houses for small retail and tourism payments. This shift protects small businesses from foreign currency volatility.
2. Disruption of Credit Card Interchange Models
Legacy credit card networks rely on high Merchant Discount Rates (MDR), often charging small business owners 1.5% to 3.5% per transaction. UPI’s account-to-account (A2A) model cuts out intermediate card issuers, reducing merchant transaction costs and increasing profit margins for small and medium enterprises (SMEs) globally.
3. Agentic AI & Programmatic Micro-Payments
As artificial intelligence transitions into autonomous agents that book flights, manage subscription services, and execute procurement routines, low-cost API-first payment rails like UPI provide the digital foundation for machine-to-machine (M2M) micro-transactions without high per-swipe fees.
The Macroeconomic Impact of UPI on Sovereign Central Banking & FX Reserves
Beyond convenience for tourists, UPI global expansion introduces macro-level changes to global cross-border capital flows and international monetary policy.
Direct Local Currency Settlement Corridors
Historically, cross-border remittances and retail transactions required converting home currencies into intermediate vehicle currencies (predominantly USD or EUR) before converting to the destination currency.
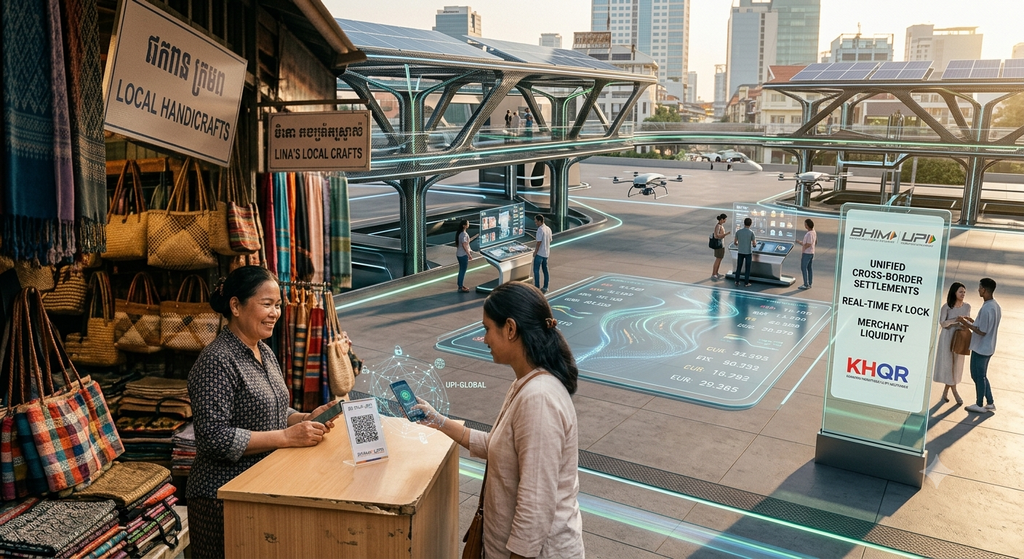
By pairing UPI with overseas real-time payment (RTP) systems-such as Singapore’s PayNow or Cambodia’s KHQR via ACLEDA Bank-transactions execute via direct local currency exchange rate pricing. This approach offers clear systemic advantages:
Lower Nostro/Vostro Balance Capital Lockups: Commercial banks no longer need to maintain high foreign exchange liquidity reserves in overseas correspondent bank accounts to settle daily retail trades.
Mitigation of Exchange Rate Spreads: Direct API linkage locks in real-time exchange rates at the moment of payment execution, protecting micro-merchants and travelers from intraday currency fluctuations.
Technical Comparison: Account-to-Account (A2A) vs. Traditional Card Networks
Understanding why foreign central banks partner with NPCI International Payments Limited (NIPL) requires analyzing the structural mechanics of Account-to-Account (A2A) networks compared to card-based systems.
Direct Routing Architecture: In traditional card schemes, a single transaction touches five distinct entities: the customer, issuing bank, card network, acquiring bank, and merchant. UPI’s account-to-account architecture uses direct API bridges between financial institution endpoints, reducing intermediary processing delays.
Software-Based Deployment: Traditional card networks require physical Point-of-Sale (POS) card terminals, which incur hardware costs, rental fees, and maintenance overheads. UPI operates on software-generated static or dynamic QR codes, dramatically lowering acquisition barriers for micro-retailers in developing digital economies.
Economic Benefits for Small & Medium Enterprises (SMEs)
While large multinational corporations rely on global corporate banking channels, small and medium enterprises often face friction in international transactions. The global rollout of UPI provides clear operational advantages for micro-businesses, local retailers, and hospitality vendors in participating international regions.
Elimination of Hardware POS Costs: Merchants in partner nations can accept digital payments simply by displaying an interoperable static or dynamic QR code (such as KHQR in Cambodia or PayNow QR in Singapore). This avoids expensive Point-of-Sale (POS) terminal rentals and hardware maintenance fees.
Instant Merchant Liquidity: Unlike traditional international credit card processing-which often delays payout clearance to merchant accounts for several business days-account-to-account systems enable faster liquidity settlement for local businesses.
Predictable Currency Conversion: Real-time foreign exchange rate locking removes pricing ambiguity, allowing micro-vendors to accept international tourist payments without risk from intraday currency fluctuations.
The Broader FinTech Ecosystem: Innovations Shaping Digital Wealth
The expansion of UPI is part of a broader shift in the financial technology landscape:
1. Credit Lines on UPI
Users can now link pre-approved credit lines from commercial banks directly to their UPI handles. This shifts micro-credit access away from physical credit cards to instant, QR-driven point-of-sale financing.
2. Conversational Voice Payments
Integrating artificial intelligence with financial applications allows users to issue voice commands in native regional languages to verify bank balances, check bills, or make peer-to-peer transfers.
3. Central Bank Digital Currencies (CBDC) Interoperability
As central banks globally develop sovereign digital currencies, UPI serves as a front-facing layer, showing how digital fiat currency can seamlessly coexist with commercial bank deposits in a single mobile wallet.
Establishing Balance Through Authentic Worship
Sant Rampal Ji Maharaj teaches that true peace of mind is achieved when an individual aligns their daily life with scripture-based worship (Satbhakti) under the guidance of a genuine spiritual guide (Tatvdarshi Sant).
Modern payment systems like UPI provide practical convenience for everyday responsibilities. However, true stability comes from cultivating inner wealth through authentic devotion. Balancing physical duties with sincere spiritual practice allows individuals to navigate a fast-paced digital world while securing lasting peace and spiritual salvation (Moksha).
FAQs on UPI Global Expansion & Financial Tech
Q1: What is UPI global expansion, and how does it work?
UPI global expansion refers to the cross-border integration of India’s Unified Payments Interface (UPI) with international banks, merchant networks, and national payment rails. It allows users to make instant, real-time payments in foreign nations directly from their home bank accounts using QR code scans or mobile numbers.
Q2: Which countries currently accept UPI payments?
UPI payments or linked instant transfers are active in 11+ nations, including the UAE, Singapore, France, Sri Lanka, Nepal, Bhutan, Mauritius, Qatar, Cambodia, Greece, and Maldives.
Q3: What are the main benefits of using UPI for international transactions?
The primary benefits include zero or low currency conversion markups, instantaneous account-to-account settlement, convenience (no need to carry excess foreign currency or international credit cards), and lower overall remittance charges.
Q4: How does UPI lower cross-border remittance costs compared to SWIFT?
Legacy systems like SWIFT involve multiple intermediary correspondent banks, each charging processing fees. UPI cross-border links directly connect sovereign central bank payment systems or payment gateways, eliminating intermediaries and lowering costs.
Q5: Can material wealth gained through fintech provide true happiness?
While financial tech provides physical ease and efficiency in daily living, spiritual masters like Sant Rampal Ji Maharaj explain that true, permanent happiness comes from inner contentment and scripture-based worship of the Supreme Almighty, rather than material accumulation.